

Tilt: Cash Advance & Credit

- 108.17K Reviews
- 4.6
- Downloads
- 5,000,000+
Our take on Tilt: Cash Advance & Credit from Appgk
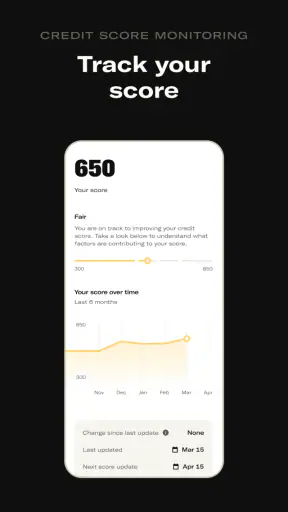
Tilt: Cash Advance & Credit caught my attention because it approaches personal finance from a more practical angle than the usual credit-score dashboard. Its central idea is simple: access to cash and credit should not be judged by one number alone. After spending time with it, I found the app most interesting when I treated it as a recurring financial tool rather than a quick fix for a short-term cash problem.
This is a free finance app from Tilt Finance, available for everyone and compatible with Android devices running version 7.0 or later. It has been around since December 4, 2017, and its current version is 7.61.0.844. That history matters because a finance app needs to feel dependable over time, not merely attractive during the first few minutes.
What the first week feels like
The first-week appeal comes from the promise of a more accessible route to financial support. Instead of making the experience feel exclusively designed for people with spotless credit histories, Tilt presents itself as an option for people whose financial situation may be more complicated. I can see why that message has connected with so many users: the app has passed five million installs, with an average rating of 4.6 from roughly three hundred thousand ratings.
That popularity does not automatically make it right for everyone, but it does suggest that Tilt is solving a problem many people recognize. The initial experience is easiest to appreciate when you have a specific reason to explore it, such as needing to understand available credit options or looking for a cash resource during an awkward gap between expenses and income.
Best Parts of Tilt: Cash Advance & Credit
Things to Keep in Mind About Tilt: Cash Advance & Credit
I would not install it simply because the idea sounds reassuring. Finance apps are most useful when they answer a real question. Before signing up, I would decide whether I am looking for short-term cash, a way to build more awareness around borrowing, or an alternative to immediately turning to a bank, credit card, or overdraft. That small bit of preparation makes the app feel more purposeful and reduces the risk of treating it like an impulse solution.
The strongest early impression is the tone. Tilt Finance focuses on the person behind the credit profile, which feels less judgmental than many conventional financial products. For someone who has been rejected elsewhere or feels that a traditional score does not describe their current circumstances, that positioning can make the first interaction less intimidating.
News and Features Related to Tilt: Cash Advance & Credit

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
At the same time, a friendly presentation should not be confused with free money. The app belongs to a category where the important questions are practical: what is available to me, what will I need to do, and what will repayment or continued use mean for my budget? I found it useful to keep those questions in front of me instead of letting the convenience of the interface make the decision for me.
A realistic everyday use case
Imagine a user whose paycheck arrives after an essential bill is due. The immediate temptation might be to use an overdraft, ask a friend, or put the expense on a credit card. Tilt can be worth checking as another possible route, particularly if the user wants to explore cash or credit without assuming that a conventional lender will be the only answer.
Don't want to read the full review?
The sensible workflow is not to open the app only when the bill is already overdue. I would review the available choices while the situation is still manageable, compare the consequences with familiar alternatives, and decide whether the repayment fits the next budget cycle. That turns Tilt from an emergency button into a planning tool.
This is also where expectations matter. An app in this category cannot remove the underlying shortage of money. It may help bridge a timing problem, but it does not make an unaffordable expense affordable. If the same gap appears every month, the better solution may be changing bill dates, reducing recurring costs, increasing income, or speaking directly with the provider. Tilt is more convincing for an occasional mismatch than for a permanent deficit.
Screenshots
What makes it different from the usual choices
Compared with a traditional bank app, Tilt feels more focused on access and flexibility than on displaying an established account relationship. A bank application is usually best when you already have checking, savings, direct deposit, and long-term money management in one place. Tilt is more relevant when the immediate concern is cash or credit access and your standard banking relationship does not feel sufficient.
Compared with a credit card, the attraction is that you are not necessarily relying on a long-standing card account with a fixed spending habit. That can be helpful for someone who wants to separate a short-term need from everyday purchases. The trade-off is that a credit card may offer clearer familiarity, broader acceptance, or a more established repayment routine, depending on the user’s situation.
Compared with an overdraft, Tilt may feel like a more deliberate choice because you can investigate it before allowing an account balance to fall below zero. Still, the right comparison is always the total financial impact, not just the speed of access. A familiar option is not automatically cheaper, and a newer option is not automatically better.
Why continued use matters more than the first impression
The real test begins after the initial curiosity fades. A finance app earns permanent space on my phone only if it helps me make better decisions repeatedly. Tilt has the potential to do that when I use it as part of a monthly review: check whether I still need access to credit, look at upcoming pressure points, and avoid borrowing simply because an option is available.
That recurring value is different from the excitement of receiving cash quickly. The useful habit is reviewing the situation before a crisis, not waiting until stress has already narrowed the choices. I would set a personal checkpoint around payday or the start of a billing cycle, then ask whether any outstanding obligation is moving in the wrong direction.
One non-obvious benefit of this approach is that it separates the decision to borrow from the emotion of an emergency. When I look at an option in advance, I can compare it with delaying a purchase, negotiating a due date, or using money already set aside. That makes the app more valuable as a decision aid than as a simple source of funds.
Another useful habit is keeping a written reason for each borrowing decision. “Covering a timing gap until income arrives” is very different from “trying to make a monthly budget work.” The first may be temporary; the second is a warning sign. Tilt cannot make that distinction for me, but using it alongside a simple note or budget can make the pattern visible.
Users should also think about whether they need one app for everything. Tilt is not a replacement for a full banking relationship, a detailed budgeting system, or professional debt guidance. Someone who wants spending categories, savings goals, bill automation, and investment tracking may find a conventional bank or dedicated budgeting app more suitable as the main financial hub.
The maintenance burden
The ongoing work is not difficult, but it is easy to underestimate. I would keep the app updated, review any account information carefully, and avoid ignoring notifications or repayment details. In finance, a neglected app can become less useful quickly because the user loses track of what was requested, what was accepted, and what needs attention next.
There is also a mental maintenance cost. Having a convenient credit or cash option nearby can make borrowing feel normal. I found that the safest approach is to treat the app as a tool that requires a reason, not as extra income. Before using it, I would write down the amount needed, the date the gap should close, and the expense that created it.
A practical rule is to check the next budget before accepting anything. If the repayment would force another essential expense onto credit, the original decision has not solved the problem; it has moved it forward. This is one of the most important trade-offs with any cash-advance or credit service, and it deserves more attention than the convenience of the application itself.
Privacy and security also deserve ordinary, ongoing care. I would use a strong device lock, keep the operating system current, and avoid reviewing sensitive financial information on a shared or unsecured device. Those steps are not special Tilt features, but they are part of using a finance app responsibly.
The app’s broad compatibility is helpful for people using older Android hardware, since the minimum requirement is Android 7.0. That said, older devices may provide a less comfortable experience than newer phones, especially if the operating system is no longer receiving regular security updates. Compatibility makes installation possible; it does not remove the need to consider device safety.
Where fatigue can set in
The first source of fatigue is repetition. If I open the app every month and see the same basic choice without gaining a clearer understanding of my finances, the novelty wears off. Tilt needs to support a better routine, not merely encourage another transaction. Its long-term usefulness depends heavily on whether I use it to anticipate problems and compare choices.
The second is uncertainty. People often want a quick yes-or-no answer when money is tight, but responsible financial decisions usually require reading conditions and thinking about repayment. Any friction in that process can feel annoying during an emergency, yet some friction is preferable to accepting an option without understanding it.
A third issue is emotional fatigue. The app’s inclusive message may feel encouraging, but it can also make borrowing feel less consequential if I focus only on being treated fairly. Fair access and affordable repayment are separate questions. I would appreciate the first while still examining the second with care.
There is also a risk of using Tilt as a substitute for repairing a damaged budget. If recurring expenses consistently exceed income, short-term access may provide relief while leaving the cause untouched. In that situation, a nonprofit debt counselor, a bank conversation, or a detailed spending review may be more valuable than another credit option.
People who prefer a single, familiar financial provider may also feel that Tilt adds another account or workflow to manage. If your bank already gives you affordable overdraft protection, a suitable credit line, and clear account controls, the advantage of adding another app may be limited. Tilt is most compelling when your existing choices are inaccessible, confusing, or poorly matched to your circumstances.
Questions I would answer before relying on it
Is it suitable for someone with limited credit history? That is one of the audiences most likely to investigate it, because Tilt’s message is built around looking beyond a single credit score. Even so, I would not assume that eligibility or affordability is guaranteed. I would use the app to explore my actual options, then judge them by the repayment effect on my budget.
Can it replace a bank account? I would not treat it that way. Its role is closer to a cash and credit resource than a complete everyday banking center. If you need deposits, routine payments, savings organization, and a broad account history in one place, a bank remains the more natural foundation.
Should I use it for recurring bills? Only if the underlying plan is sustainable. A one-time timing mismatch is easier to manage than a monthly dependence on borrowed money. If the same bill requires assistance repeatedly, I would first look for a permanent adjustment rather than making Tilt part of the bill-payment cycle.
Is it appropriate for emergencies? It can be worth considering when the emergency is specific and the repayment plan is realistic. I would not use it for an open-ended crisis, discretionary spending, or a situation where repayment depends on taking out another form of credit. The app may widen the choices, but it cannot guarantee that borrowing is the right answer.
Will it remain useful after the first month? For me, yes, but only with a deliberate routine. Checking available options without tracking why I am checking them would quickly become pointless. The lasting value comes from using it before a financial pinch, comparing it with alternatives, and recognizing when the correct decision is not to borrow.
Who should make room for it
Tilt makes the most sense for adults who want to investigate cash or credit access outside the narrow assumptions of a traditional credit-score-first experience. It may also suit someone who needs a separate place to evaluate a short-term financial gap instead of immediately using a bank overdraft or an everyday credit card.
I would recommend it cautiously to a friend who has a clear, temporary need and enough income visibility to plan repayment. I would also recommend setting a personal borrowing limit before opening the app, even if that limit is simply “only for essential timing gaps.” That boundary helps preserve the app’s usefulness without letting it become an automatic spending fallback.
I would steer away from it as a primary solution for someone already juggling several debts, missing payments, or borrowing to cover basic living costs every month. That person needs a broader financial plan, not just another access point. The same applies to anyone who dislikes managing multiple financial services or rarely reads repayment information carefully.
My long-term verdict
After the first-week appeal fades, Tilt: Cash Advance & Credit remains worthwhile when it is used with discipline. Its strongest quality is not the promise of instant relief; it is the possibility of giving people another way to examine cash and credit access when a conventional score does not tell the whole story. The free price and wide availability make it easy to try, while its established presence and large user base make it feel less experimental than a brand-new finance app.
Still, I would not call it a universal replacement for a bank, credit card, overdraft facility, or budgeting app. Each alternative may be better in a specific situation, especially when you already have clear terms, a stable repayment habit, and useful account tools elsewhere. Tilt earns its place when it fills a genuine gap rather than when it simply adds another borrowing button.
My final recommendation is to install it with a plan. Use it to compare choices, record the reason for borrowing, and check whether the next month becomes easier or tighter afterward. The lasting value is in the habit of making a deliberate decision, not in treating available credit as spare income. Used that way, Tilt Finance can be a practical addition for people who need more flexible options. Used without that discipline, it may only postpone the financial problem that brought you to it.
Tilt: Cash Advance & Credit FAQ
What is Tilt: Cash Advance & Credit, and how does it work?
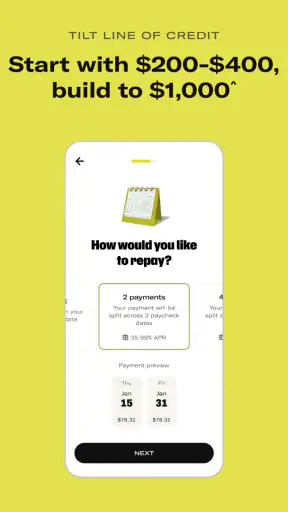
Tilt: Cash Advance & Credit is a financial app designed to help eligible users access money before their regular payday and manage short-term cash-flow needs. After creating an account, you may be asked to connect financial information and provide identity details. The app reviews your information, displays any available options, and explains applicable repayment terms, fees, and requirements before you accept an advance.
How much money can I borrow with Tilt, and will everyone be approved?
The amount available through Tilt can vary considerably depending on factors such as your income, account activity, employment information, repayment history, and other eligibility criteria. Approval is not guaranteed, and the app may offer different limits to different users. Before accepting an advance, carefully review the amount offered, the total repayment obligation, the due date, and any associated charges.
Does Tilt charge fees or interest for cash advances and credit services?
Costs may depend on the specific product, your eligibility, the delivery method you choose, and the terms shown in the app. Some services can involve subscription charges, expedited-transfer fees, finance charges, or other costs. Do not assume that an advance is free simply because the app presents it as convenient. Read the complete disclosure and confirm the total amount you will repay before proceeding.
When will I receive the money, and how is repayment handled?
Delivery time depends on the option selected, your bank, verification status, weekends, holidays, and whether you choose standard or faster delivery. Repayment is generally scheduled according to the terms displayed when you accept the advance and may be collected from a linked bank account or another authorized payment method. Keep sufficient funds available and check the repayment date to avoid failed payments or additional charges.
Is Tilt safe to use, and what personal information does it require?
Tilt may request sensitive information such as your name, contact details, identification data, income information, banking credentials, and transaction history to verify your identity and assess eligibility. Before signing up, review the app’s privacy policy, security practices, permissions, and data-sharing disclosures. Download the application only from an official app store, use a strong password, and never provide account details through unofficial links or messages.











